Can You Get a Joint Mortgage with Friends? A Clear Guide for UK Buyers
Meta Description: Thinking of buying a home with friends? Learn how joint mortgages work, options, risks, and what to consider in the UK market. Can You Get a Joint Mortgage with Friends? Buying a home is a big step, and for many people in the UK, getting on the property ladder can be challenging. Sometimes, […]
Can You Get a Mortgage While on Probation?
Being on probation doesn’t automatically rule you out from getting a mortgage, but it can make the process a little tougher. UK mortgage lenders want to see evidence of stable income and employment, so they may apply stricter criteria or ask for a bigger deposit if you are applying for a mortgage while on probation. […]
Can You Get a Mortgage if You Change Jobs?
Getting a mortgage is a big step, and many people worry about how changing jobs might affect their chances of approval. Whether you’re moving into a new role, switching employers, or starting a completely new career, you might be wondering, can I still get a mortgage? Changing jobs does not automatically mean you cannot get […]
How Many Mortgage Applications Should You Make?
Applying for a mortgage can feel overwhelming, especially if you’re unsure how many mortgage applications you should make. Making too many applications might affect your credit score, but applying for just one and getting rejected could leave you stuck without a mortgage. So, how many mortgage applications should you make in the UK? In this […]
What Is a Mortgage Broker and What Do They Do?
Buying a home, whether it’s your first property or an investment, can feel overwhelming. With so many UK mortgage deals, mortgage lenders and mortgage products to choose from, it’s easy to get lost in the details. That’s where a mortgage broker comes in. But what is a mortgage broker and what do they do? In […]
Can Critical Illness Cover Help Protect Your Mortgage? A Clear Guide for UK Homeowners
Can Critical Illness Cover Help Protect Your Mortgage? Buying a home is one of the biggest financial commitments most people make in their lives. For many in the UK, a mortgage is essential to buying a property, whether it’s for your main home or a buy-to-let investment. While you plan your finances carefully, it’s just […]
Is Mortgage Protection Insurance Worth It? A Clear Guide for UK Homeowners
Buying a home or a buy-to-let property is likely one of the biggest financial decisions you’ll make. Alongside choosing the right mortgage, many UK homeowners and landlords ask: Is mortgage protection insurance worth it? Mortgage protection insurance can cover your mortgage payments if life takes an unexpected turn – but is it right for you? […]
How to Protect Your Home and Family Financially
Buying a home is one of the biggest financial decisions many people make. Whether it’s your first residential property or a buy-to-let investment, securing your home and family against financial risks is crucial. In the UK, where mortgage types vary and interest rates can change, knowing how to protect your home and family financially can […]
Should Couples Both Have Protection Insurance?
Buying a home is one of the biggest financial decisions most people make in their lifetime. For couples, this often means taking out a mortgage together. While securing the loan is a major step, it’s equally important to think about how to protect that mortgage if something unexpected happens. One common question UK homebuyers ask […]
What Happens on Completion Day? A Clear Guide for UK Mortgage Borrowers
Buying a home or a buy-to-let property is an exciting milestone, but it can also be confusing, especially when it comes to the legal and financial steps involved. One of the most important stages in the UK mortgage process is completion day. This is the day the property officially becomes yours and your mortgage begins. […]
What Happens to Your Mortgage If You Become Ill?
Life is unpredictable, and unforeseen illness can happen to anyone. If you have a mortgage, it’s natural to worry about what happens to your mortgage if you become ill, how illness might affect your ability to keep up with payments, and what support may be available. Whether you have a residential mortgage, buy-to-let property, fixed-rate […]
Can a Mortgage Be Declined After an Agreement in Principle?
Buying a home is one of the most significant financial decisions many people make. For most buyers, getting a mortgage is a necessary step, and often the first stage is obtaining an Agreement in Principle (AIP). But can a mortgage be declined after an Agreement in Principle? Yes, it is possible. An Agreement in Principle […]
What Can Delay a Mortgage Application?
Applying for a mortgage can be an exciting step towards owning your home or expanding your property portfolio. However, the process doesn’t always run smoothly. Mortgage application delays in the UK are common and can be frustrating especially if you’re eager to complete a house purchase or refinance your property. Understanding what can delay a […]
What Does a Solicitor Do During a House Purchase? A Simple Guide for UK Buyers
Buying a house is one of the biggest financial decisions you’ll ever make. Whether it’s your first home, a buy-to-let investment, or upgrading to a bigger place, understanding the house-buying process can make things much easier. One key part of this process is working with a solicitor. But what exactly does a solicitor do during […]
What Happens After a Mortgage Offer Is Issued? A Clear Guide for UK Buyers
Securing a mortgage offer feels like a big step forward when buying a home or investing in property. But what happens next? Understanding what happens after a mortgage offer is issued in the UK can help you prepare for the next stages of the property purchase and avoid unexpected delays. Whether you’re buying your first […]
Can Parents Help with a Mortgage Deposit? A Simple Guide for UK Homebuyers
Buying a home is an exciting milestone, but saving for a mortgage deposit can be one of the biggest hurdles. For many first-time buyers, the amount needed for a deposit feels out of reach. A common question that comes up is: can parents help with a mortgage deposit? The short answer is yes, but there […]
What Proof is Needed for a Gifted Deposit?
Buying a home is one of the most significant financial decisions you’ll make. For many UK buyers, especially first-time buyers, a gifted deposit can be a helpful way to get on the property ladder or secure a buy-to-let mortgage. However, when you use a gifted deposit, mortgage lenders will require proof to ensure everything is […]
Can Gifted Deposits Be Used for a Mortgage?
Saving for a mortgage deposit can be a big challenge when buying a home. Many people wonder if they can use a gifted deposit that is, money given to them by another person to help with their mortgage. The good news is that gifted deposits are often accepted by UK mortgage lenders. However, important rules […]
Is a Bigger Deposit Always Better?
When it comes to getting a mortgage in the UK, one of the first questions many people ask is: “Is a bigger deposit always better?” It’s a common assumption that putting down a larger deposit will save you money and make the process smoother. But is that always true? The simple answer is: not necessarily. […]
What is Loan-to-Value (LTV)? A Simple Guide to UK Mortgages
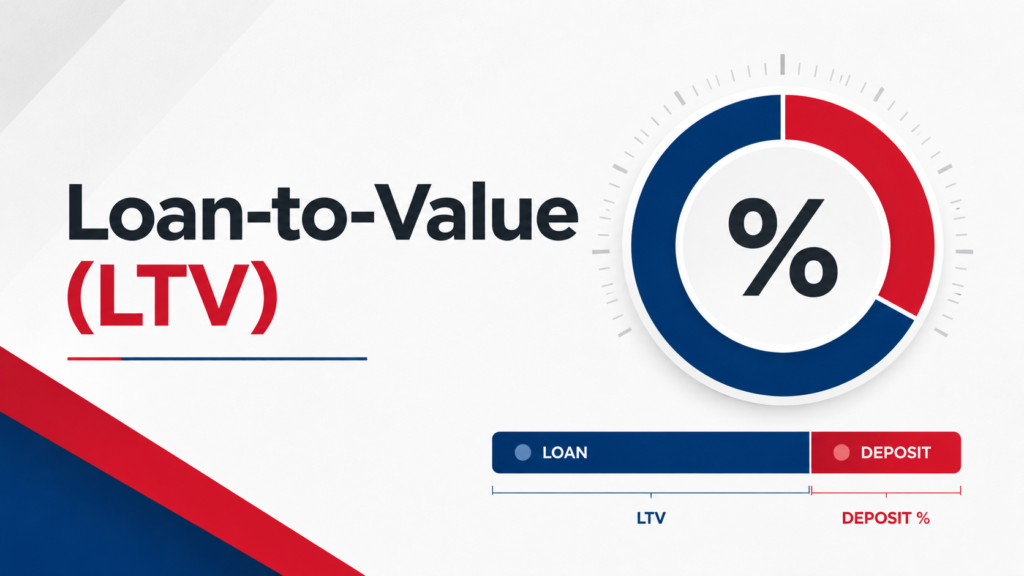
What is Loan-to-Value (LTV)? Buying a home or an investment property usually involves taking out a mortgage. When applying for a mortgage in the UK, one term you’ll often hear is Loan-to-Value, or LTV. But what exactly does LTV mean, and why does it matter? In this guide, we’ll explain what loan-to-value is in a […]
Do Lenders Include Commission Income When Assessing Mortgage Applications?
When you’re applying for a mortgage in the UK, understanding what counts as income is essential. This is especially true if you receive commission payments as part of your earnings. You might be wondering, do mortgage lenders include commission income? This blog post will explain how lenders view commission income, how it impacts your mortgage […]
How Do Mortgage Lenders Calculate Affordability?
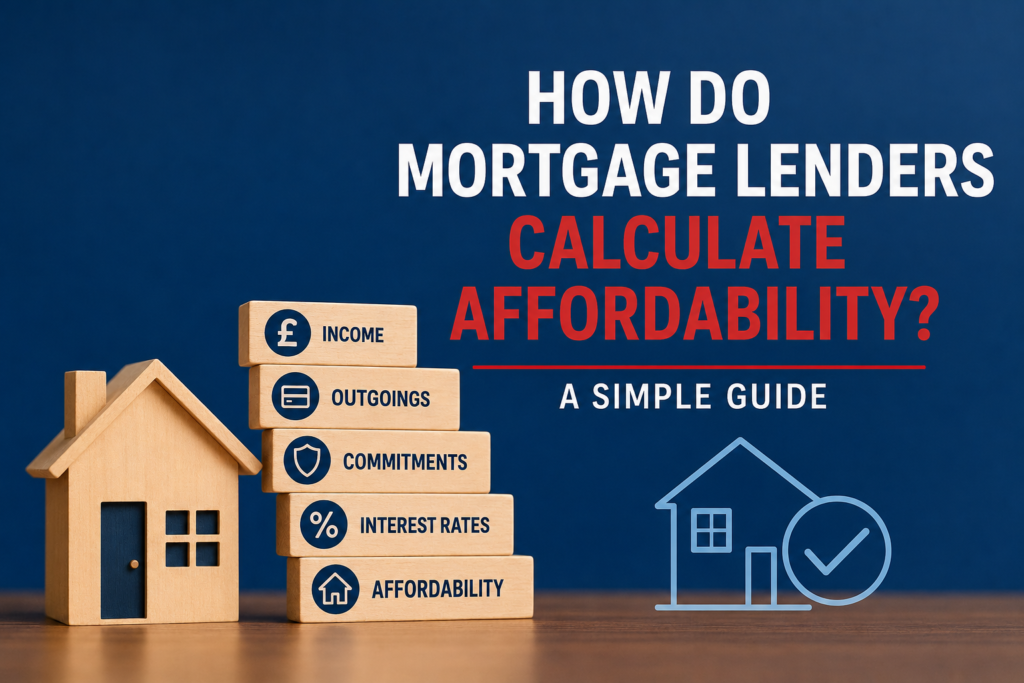
Mortgage affordability is about more than multiplying your salary by four or checking whether you can manage today’s monthly repayment. Before approving a mortgage, a lender will assess whether you are likely to afford the payments throughout the mortgage term. This normally includes reviewing your income, household expenditure, existing debts, credit history, deposit and the […]
Specialist Mortgages for Complex Income Explained
A complicated income structure does not necessarily mean you cannot get a mortgage. Many applicants earn enough to afford a property but do not receive one simple monthly salary. You might be self-employed, operate through a limited company, work on contracts, earn commission or receive income from several sources. A standard automated assessment may not […]
Can I Improve My Credit Score Before Applying?
Yes, you can take practical steps to improve your credit profile before applying for a mortgage. Checking your credit reports, correcting inaccurate information, paying commitments on time and reducing reliance on borrowing may all strengthen your position. However, improving a credit score does not automatically guarantee mortgage approval or a lower interest rate. Mortgage lenders […]
Can Payday Loans Affect Your Mortgage Application?
Payday loans can affect a mortgage application in the UK, even when they have been repaid on time. Mortgage lenders assess more than your income and deposit. They may review your credit history, recent borrowing, current debts, bank statements and monthly expenditure to decide whether the proposed mortgage is affordable. A payday loan on your […]
How Mortgage Lenders Assess Adverse Credit Applications
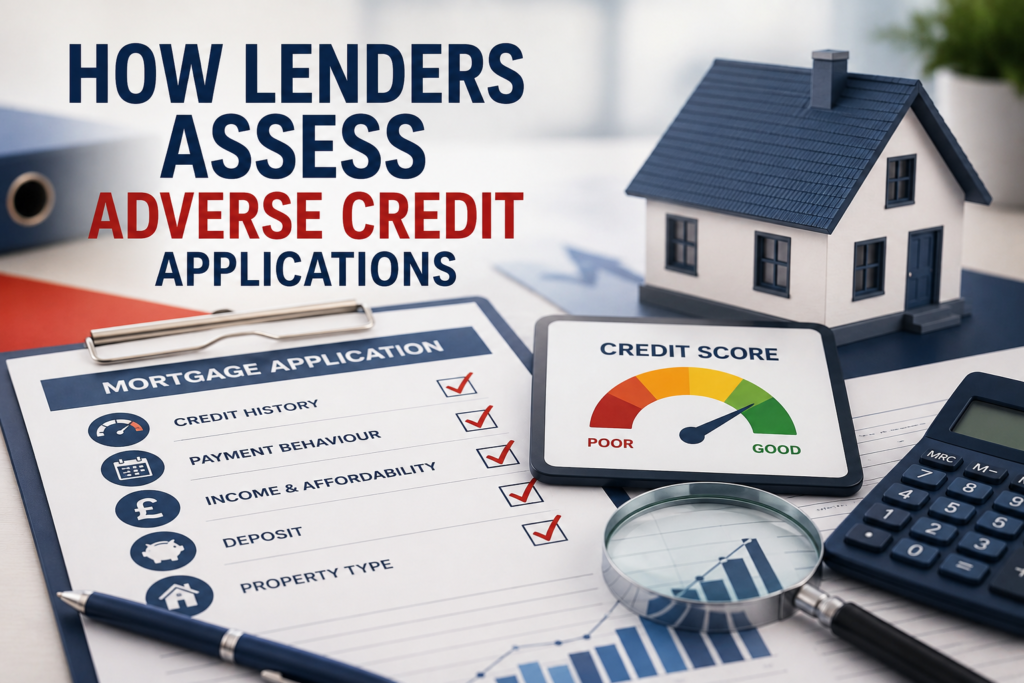
Applying for a mortgage can feel more complicated when your credit history includes missed payments, defaults, County Court Judgments or another form of adverse credit. However, adverse credit does not automatically mean that every mortgage lender will decline your application. UK lenders use different eligibility rules. Some accept only minor or historic credit problems, while […]
Can I Get a Mortgage After Bankruptcy?
Going through bankruptcy can feel overwhelming, particularly when you begin thinking about your future financial plans. You may be wondering: Can I get a mortgage after bankruptcy? The answer is that getting a mortgage after bankruptcy may be possible, but it usually requires time, careful financial preparation and an application to a lender whose criteria […]
Topic: Can I Get a Mortgage After a CCJ?
Can I Get a Mortgage After a CCJ? Having a County Court Judgment can feel like a major roadblock when trying to secure a mortgage in the UK. Whether you are looking to buy your first home, remortgage your current property or invest in a buy-to-let property, you may be concerned about how a CCJ […]
Can Retained Profits Help Mortgage Affordability?
For many company directors and self-employed business owners, the income shown on a personal tax return does not always reflect the full financial strength of the business. You may keep some of your company’s profit inside the business rather than withdrawing everything as salary or dividends. These retained profits can support business growth and financial […]
What to Do If Your Income Fluctuates When Applying for a UK Mortgage
What If My Income Fluctuates? Understanding How Variable Earnings Affect UK Mortgages When applying for a mortgage in the UK, one of the most important factors lenders consider is your income. But what happens if your income is not consistent every month? For many people, including self-employed workers, freelancers, contractors, commission-based employees and people in […]
Can I Get a Mortgage if I’ve Recently Become Self-Employed?
Recently becoming self-employed does not automatically stop you from getting a mortgage. However, your options may be more limited because lenders have less financial history to use when assessing your income. The strength of your application will depend on how long you have traded, how your business is performing and what evidence you can provide. […]
What Mortgage Lenders Look for From Self-Employed Applicants
Getting a mortgage when you are self-employed can feel more complicated than applying as a salaried employee. The difference is usually not that mortgage lenders consider self-employed applicants unsuitable. It is that self-employed income can be structured in several ways and may change from one year to the next. Mortgage lenders therefore need clear evidence […]
Mortgages for Contractors Explained Simply
Getting a mortgage as a contractor can seem more complicated than applying as a permanent employee. Contractors may work through fixed-term agreements, umbrella companies or their own limited companies. Their income can therefore appear less predictable to lenders, even when they earn consistently. The good news is that mortgages for contractors are available in the […]
Can Limited Company Directors Get a Mortgage Easily?
Getting a mortgage as a limited company director is entirely possible, but the application may require more preparation than it would for someone receiving a straightforward monthly salary. Directors often take income through a combination of salary and dividends. Some also leave profits within the business rather than withdrawing everything personally. As lenders assess these […]
Can Directors Use Salary and Dividends for Mortgage Affordability?
Yes, company directors can often use a combination of salary and dividends for mortgage affordability. However, directors are frequently assessed differently from standard employees. The lender may examine not only the income paid to you personally but also your shareholding, company accounts, recent performance and whether your dividends appear sustainable. Understanding these requirements before applying […]
How Many Years of Accounts Do I Need for a Mortgage?
Applying for a mortgage in the UK can feel overwhelming, especially if you are self-employed, a company director, or running your own business. One of the most common questions applicants ask is: “How many years of accounts do I need for a mortgage?” In most cases, mortgage lenders may ask self-employed applicants for two to […]
What Is a Product Transfer Mortgage? A Simple Guide for UK Homeowners
What Is a Product Transfer Mortgage? If you have a mortgage in the UK, you may have heard the term “product transfer mortgage” or “mortgage rate switch”. But what exactly does a product transfer mean? Could it reduce your mortgage payments or make your monthly costs more predictable? A product transfer allows you to switch […]
Can Self-Employed People Get a Mortgage?
If you’re self-employed in the UK and wondering, “Can self-employed people get a mortgage?”, the answer is yes. Whether you’re a sole trader, freelancer, contractor, limited company director, or business owner, many UK lenders offer self-employed mortgages for both residential and buy-to-let properties. However, the mortgage application process for self-employed borrowers is often different from […]
Is It Worth Remortgaging Early? A Simple Guide for UK Homeowners
Refined Word doc is ready. Now here is the same treatment applied to your remortgaging content: Slug URL: is-it-worth-remortgaging-early-uk-guide Primary Keyword: remortgaging early UK Secondary Keywords: is it worth remortgaging early, early repayment charges UK, remortgage before deal ends, release equity remortgage, fixed rate remortgage UK, buy to let remortgage early, remortgage savings calculator UK, […]
How Long Does Remortgaging Take? A Clear Guide for UK Homeowners
How Long Does Remortgaging Take? If you are thinking about remortgaging your property, one of the key questions on your mind might be: how long does remortgaging take? Whether you want to switch from a fixed rate to a variable rate, move from a residential mortgage to a buy-to-let mortgage, or simply secure a better […]